
FOMC Minutes Take Center Stage as ADI Drive the Next Validation Round for AI Hardware | WEEX Weekly Market Preview (August 17-August 21, 2026)

 Prefer us on Google


Key Themes This Week
This week’s macro focus is less about backward-looking inflation prints and more about whether the Fed minutes and high-frequency growth data can reshape rate expectations heading into September. On the industry side, earnings from optical module manufacturing, test and measurement, analog semiconductors will help determine whether AI capex momentum is still broadening across the supply chain. If the minutes lean hawkish and PMI data remains resilient, markets may reprice a “firm growth, delayed easing” backdrop; if the tone is more balanced and corporate guidance holds up, growth equities could retain room for valuation repair.
August 17 | Monday
Fabrinet Q4 and FY2026 Results | ★★★★☆
As a key manufacturing partner in high-end optical communications and precision photonics, Fabrinet’s results should provide an early read on AI data-center optical module demand, component utilization, and upstream capacity conditions. If orders, utilization, and management guidance improve in tandem, the market may gain further confidence that the AI optical chain has not materially cooled after the second quarter.
Potential Trading Instruments:
Optical Manufacturing: FNON-USDT
August 18 | Tuesday
Keysight FY2026 Q3 Results | ★★★☆☆
Keysight’s earnings will serve more as a midstream validation point, with investors watching whether advanced test and measurement demand continues to benefit from AI server, networking, and semiconductor R&D spending. Stronger orders and guidance would reinforce the view that AI infrastructure spending is extending beyond GPUs into system verification and broader hardware enablement.
Potential Trading Instruments:
Test and Measurement: KEYSON-USDT
August 19 | Wednesday | Key Trading Day
FOMC July Meeting Minutes | ★★★★★
The key issue in this release is not simply the Fed’s inflation language, but the degree of internal divergence over the policy path and the durability of U.S. growth. A hawkish set of minutes could push long-end Treasury yields and the U.S. dollar higher, tightening valuation conditions for growth assets; a more neutral tone could allow risk assets to extend their consolidation recovery.
Potential Trading Instruments:
Nasdaq Exposure: QQQB-USDT
Analog Devices FY2026 Q3 Results | ★★★★☆
The market will focus on whether demand remains durable across industrial, data-center, power management, and edge-AI exposure. If the analog cycle recovery and AI-linked contribution improve at the same time, semiconductor leadership could broaden further from compute leaders into analog, power, and industrial automation names.
Potential Trading Instruments:
Analog Semiconductors: ADION-USDT
August 20 | Thursday
Walmart FY2027 Q2 Results | ★★★★☆
Walmart’s quarterly results matter beyond retail alone, as they offer an important lens into U.S. consumer resilience, e-commerce penetration, and the expansion of higher-margin businesses such as advertising and membership. If the revenue mix continues shifting toward e-commerce, membership, and ad monetization, the market may grow more comfortable with the view that the U.S. consumer slowdown remains contained.
Potential Trading Instruments:
U.S. Consumer Bellwether: WMTON-USDT
August 21 | Friday
U.S. August Flash PMI | ★★★★☆
Friday’s U.S. Flash PMI will be one of the week’s most important high-frequency growth indicators, shaping views on whether the U.S. economy remains in expansion and whether price pressures are reaccelerating. If both activity and price components surprise to the upside, the market may lean further into a “resilient growth, later easing” scenario; a softer print would help ease upward pressure on yields.
Potential Trading Instruments:
Nasdaq Exposure: QQQB-USDT
Trading Roadmap This Week
Macro: FOMC minutes will shape whether rate expectations tilt more hawkish again, while U.S. Flash PMI will help validate the direction of global liquidity and growth resilience.
AI: Fabrinet, Keysight, and ADI will test whether AI capex continues to broaden across optical communications, test equipment, and analog semiconductors.
Consumer and Risk Appetite: Walmart’s results will provide an important read on U.S. consumption quality and platform-style retail profitability, influencing how confidently the market embraces the soft-landing narrative.
-- Price
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like
WEEX Exclusive:FOMC Minutes Take Center Stage as ADI Drive the Next Validation Round for AI Hardware | WEEX Weekly Market Preview (August 17-August 21, 2026)
CPI, PPI and TSMC Earnings Recap | WEEX Weekly Market Recap (2026.10.12-10.16)
WEEX Weekly Market Recap focuses on CPI, PPI, TSMC earnings, AI financing pressure, BTC’s key support, the PYTH buyback narrative, L2 and privacy-token rotation, and crypto-finance strength. Risk assets first pulled back on oil, inflation, and AI valuation pressure, then rebounded quickly after the market digested the PPI shock.
Stocks and Crypto Rebound After Hot PPI | WEEX TradFi Daily Brief (October 16, 2026)
On October 15, September PPI rose 6.3% year on year, the highest in more than four years, briefly lifting hike expectations and triggering a short drop in equities and crypto. After the market digested the print, risk assets rebounded from the sell-off and the three major indexes closed higher. Bitcoin briefly broke below $80,000 and recovered to the $82,000–$83,000 range. CoreWeave fell sharply on bond pressure and then closed higher, while crypto-finance stocks and some L2 tokens strengthened. October 16 focus turns to industrial production and import-export prices.
Hot CPI Lifts Hike Bets; Risk Assets Pull Back | WEEX TradFi Daily(October 15, 2026)
Major indexes closed lower on October 14, with the Nasdaq leading the decline. September unadjusted CPI rose to 3.7% year on year, above forecasts, and core CPI also beat expectations. Traders sharply raised this month’s hike probability to about 43.7% and fully priced two more hikes by the end of January. Chip stocks were sold again. Bitcoin broke below $83,000 and last traded near $81,700, while spot gold and silver fell. Crypto-related stocks were under pressure, but PYTH rose against the tape. October 15 brings PPI, retail sales and key
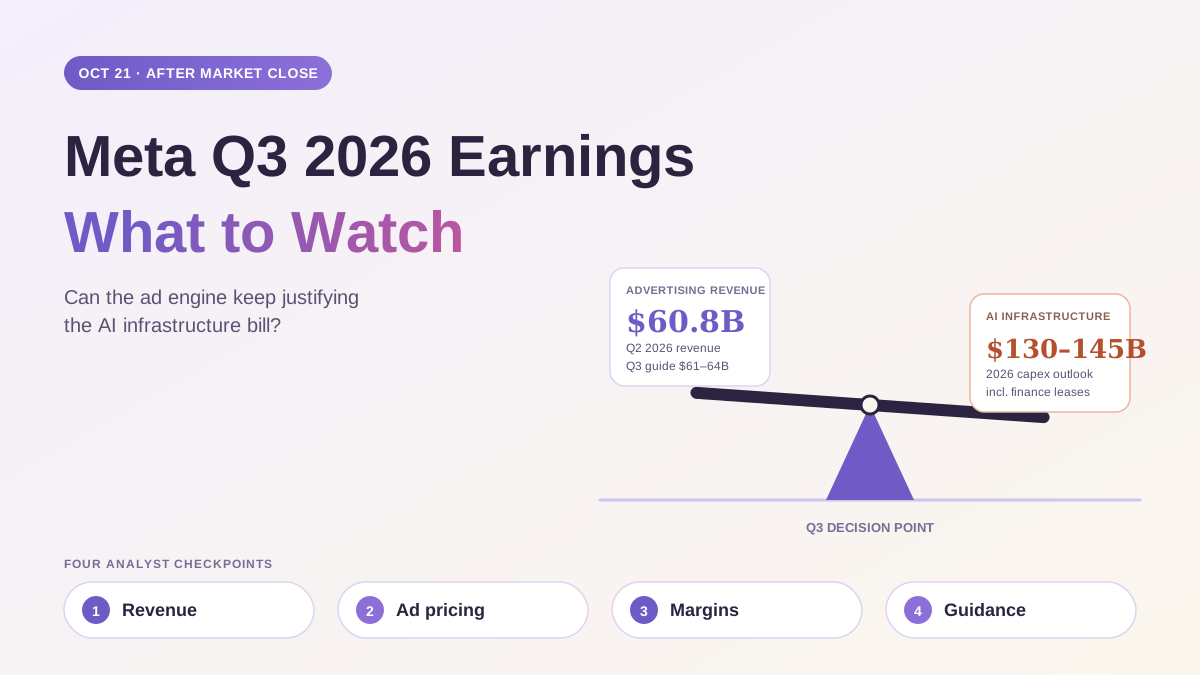
Meta Stock Earnings: What to Watch in Meta Platforms’ Q3 2026 Results
Meta reports Q3 2026 results on October 21. See the advertising, AI spending, margin, and guidance signals that could move META stock.
Indexes Fall as Bank Earnings Diverge| WEEX TradFi Daily Brief (October 14, 2026)
Major indexes closed lower on October 13 as mixed bank earnings and pressure on chip stocks weighed on sentiment, while Microsoft and Apple both rose to record closing highs. Citigroup fell more than 5% after trading revenue missed expectations. Bitcoin rallied to about $88,000 before stalling, while whale holdings shifted back toward accumulation. Ethereum L2 and privacy tokens strengthened. On October 14, markets will focus on CPI, bank earnings and ASML’s report.
Oil Spikes to $107; Bank Earnings in Focus | WEEX TradFi Daily Brief (October 13, 2026)
Markets on October 13 continued to price oil, inflation expectations and major earnings. Brent crude climbed as high as $107.25 per barrel, with supply concerns lifting inflation expectations and pressuring high-beta technology and crypto assets. Bitcoin briefly rose to $84,348 before pulling back, while equity-market performance remained divided as semiconductors, optical networking and memory stocks weakened. Today’s focus turns to Apple’s smart-home event and earnings from JPMorgan, Goldman Sachs, Wells Fargo and
Inflation Data, AI Chip Earnings| WEEX Weekly MarketPreview (October 12-October 16, 2026)
WEEX Weekly Market Hotspot Preview focuses on the PUMP unlock, the start of financial earnings, CPI, ASML earnings, PPI, retail sales, TSMC earnings, and Fed Chair Warsh’s annual-meeting fireside chat. The main themes are inflation repricing, financial-earnings validation, AI chip demand confirmation, and crypto supply pressure.
Bitcoin Tests $85K Resistance; STRK Surges | WEEX TradFi Daily Brief (October 12, 2026)
Bitcoin traded near $83,700 and is testing the $84,000–$85,000 cost-cluster zone. In crypto, L2 scaling, ZK modularity, high-performance L1s, gaming and DePIN were relatively active as capital rotated from pure meme trades toward infrastructure narratives. In equities, NVIDIA’s market value is approaching $6 trillion, supported by AI infrastructure demand, while optical modules and fiber names were relatively resilient. Bond markets are closed on October 12 ET for the holiday, while equities trade as normal; the pause in yield pricing may amplify intraday volatility.
High Yields Pressure Tech as PYTH Buyback Expectations Rise | WEEX Weekly Market Recap (October 5-October 9, 2026)
WEEX Weekly Market Recap focuses on elevated long-end yields, AI compute-chain divergence, crude rebound, BTC weakness, and PYTH buyback expectations. The week’s main thread was high rates pressuring valuations, AI infrastructure validation, and high-beta crypto rotation.
Long-Bond Highs Pressure Tech| WEEX TradFi Daily Brief (October 9, 2026)
Indexes were mixed on October 8 ET. The long-bond yield touched about 5.35% intraday, near levels last seen in 2002. OpenAI’s annualized revenue of about $50 billion came in below higher figures that had circulated, pressuring tech and chip names. Nasdaq fell clearly, while Dow edged higher. Energy led, with WTI up about 3.2% to about $91. Bitcoin pulled back from about $86,000 and traded near $81,000, down about 5%. September PPI is the focus on October 9.
September Fed Minutes Point to Another Hike This Year| WEEX TradFi Daily Brief (October 8, 2026)
Major equity indexes closed lower on October 7 ET. Long-end yields rose again, and the 30-year yield hit a roughly 24-year high. September Fed minutes showed most participants thought another increase in the federal funds target range before year-end could be appropriate. CME pricing for a 25 bp hike at the October 27–28 meeting has fallen below 20%, far below about 70% in the days after the September decision. Bitcoin traded near $83,300. The October 8 focus is jobless claims and pre-market earnings from Pepsi and Delta.
What Is Warren Buffett’s S&P 500 Investing Advice? Key Lessons for Volatile Markets
Learn Warren Buffett’s S&P 500 index fund advice, how the 90/10 rule works, and how to build a long-term plan for volatile markets.
S&P 500 and Nasdaq Hit New Highs| WEEX TradFi Daily Brief (October 7, 2026)
Major equity indexes closed higher on October 6 ET. The S&P 500 and Nasdaq both set closing highs as long-end yields eased and oil stabilized, shifting capital from rate worries toward earnings. Constellation Energy led on a long-term power agreement to supply Google, while tokenized-securities platform Securitize jumped early after signing a tech partnership. Bitcoin held near $86,000, LayerZero led majors, and Anvil surged after an institutional purchase of governance tokens. Applied Digital reports after the close on October 7 ET, while markets also track policy-meeting minutes and TOKEN2049 industry headlines.
Nasdaq Hits Another High| WEEX TradFi Daily Brief (October 6, 2026)
Major equity indexes closed higher on October 5 ET, and the Nasdaq set another record high. Tech drew inflows after weak labor data cooled rate-hike expectations, but the 10-year and 30-year yields rose intraday to about 5.34% and 5.70%. The services prices index rose to 74.0, a four-year high, so the rate overhang has not cleared. EWZ and PBR jumped on election and resource-discovery narratives, while SpaceX hit a stage high. Bitcoin traded near $86,000. On October 6 ET, markets will watch Amazon’s fall Prime event and early sales signals for consumer-sector pricing.
FOMC Minutes,and TOKEN2049 Set the Tone | WEEX Weekly Market Hotspot Preview (October 5-October 9, 2026)
WEEX Weekly Market Hotspot Preview focuses on ISM Services PMI, Glamsterdam Sepolia activation, FOMC minutes, Applied Digital earnings, TOKEN2049, PepsiCo and Delta earnings, and preliminary Michigan consumer sentiment. The week’s core narrative centers on rate-path repricing, AI data-center demand validation, institutional crypto narratives, and consumer-resilience signals.
NVIDIA Hit a Record High Last Week| WEEX TradFi Daily Brief (October 5, 2026)
On October 5, equity markets are in a watch window between labor-data volatility and the formal start of Q3 earnings. Bitcoin traded near $86,000 and Ethereum near $2,720, with majors moving in a narrow weekend range. PUMP broke above $0.0064 to another stage high; AgenC (AGENC) gained trading support, while STONK strengthened on a community-coin rewards mechanism. NVIDIA touched an intraday record high last Friday, and optical modules plus AI compute remain the main flow. September ISM Services PMI is due at 10:00 ET on October 5, while consumer and AI-infrastructure earnings this week will keep testing demand resilience.
PCE and Micron Drive Rate Trades| WEEX Weekly Market Recap (September 28-October 2, 2026)
WEEX Weekly Market Recap focuses on PCE, payrolls, JOLTS job openings, OpenAI DevDay, The AI Conference, Micron earnings, Accenture earnings, Bitcoin Treasuries Conference, and the NEAR Intents security incident. The week’s core narrative centered on rate-path repricing, AI order validation, AI memory demand, and crypto security risk.
Oil Supply Premium Lifts Energy Stocks| WEEX TradFi Daily (October 2, 2026)
Markets on October 2 are focused on oil, long-end yields and payroll data. Major equity indexes closed slightly higher on October 1 after being pressured intraday by a spike in long-end yields, with AI and energy helping support risk appetite. Accenture (ACN) jumped after AI-related bookings, revenue and full-year guidance topped expectations, while Nike (NKE) fell after hours on weaker sales. Brent crude broke above $102 and energy stocks strengthened. Bitcoin traded near $83,500. Markets are also digesting the NEAR Intents security incident and expectations for Monad’s privacy-service reveal.
Micron’s Strong Guidance Meets Long-Bond Pressure|WEEX Market (October 1, 2026)
Markets on October 1 are focused on long-end yields, consumer earnings and consulting earnings. August PCE rose 3.4% year over year and core PCE 3.0%, both below forecasts, while implied odds of another policy-rate hike fell to about 36%. Still, the 10-year Treasury yield climbed to about 5.29%, a high since 2007, keeping pressure on long-duration risk assets. Micron beat on results and next-quarter guidance, but the after-hours gain was limited. Bitcoin traded near $83,600. Investors now watch jobless claims at 08:30 ET, Accenture before the open and Nike after the close.
30-Year Yield Hits a High Since 2002| WEEX TradFi Daily(September 30, 2026)
Markets on September 30 are focused on long-end yields, inflation data and memory earnings. Major equity indexes closed lower on September 29. The 30-year Treasury yield topped 5.61% intraday, its highest level since June 2002, and closed near 5.59%, keeping pressure on long-duration growth valuations. OpenAI is reportedly discussing a funding round of at least $30 billion at a target valuation of about $1.4 trillion; OPENAI futures spiked and then faded pre-market, trading near $1,628 at the source snapshot. Brent fell to about $96, WTI was near $89, and Bitcoin was around $83,500. ADP data are due at 08:15 ET and August PCE at 08:30 ET; Micron’s after-hours report will test the memory cycle and AI demand.
10-Year Yield Breaks 5%| WEEX TradFi Daily(September 29, 2026)
Global markets on September 29 focused on the 10-year yield breaking above 5% and Anthropic’s IPO filing. On September 28, all three major equity indexes closed lower, with semiconductors and optical communications among the sectors that retreated. Anthropic’s filing showed high growth alongside large losses and $518 billion in cloud commitments. Its tokenized share traded near $2,002, down about 2% in 24 hours. Spot gold approached a two-month low near $4,118, while Bitcoin traded near $83,500.
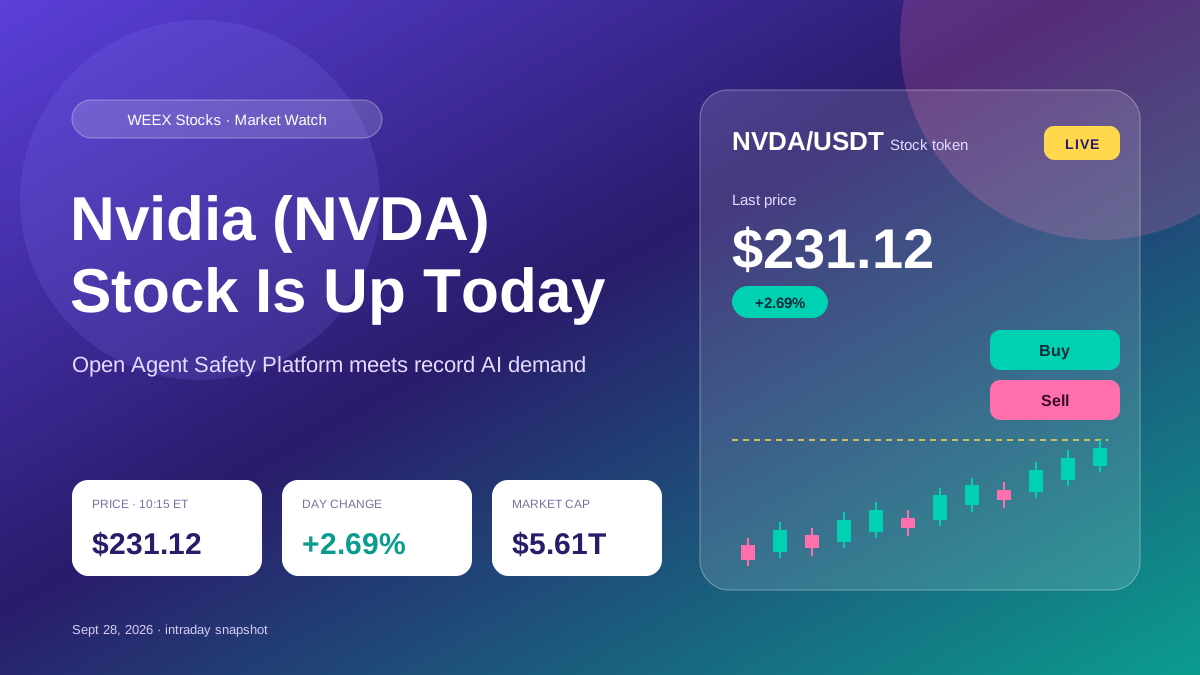
Why Is Nvidia (NVDA) Stock Up Today? New AI Agent Safety Platform Fuels the Rally
Why is Nvidia stock up today? Explore the AI agent safety launch, Nvidia’s growth outlook, key risks and how the NVDA token works on WEEX.
PCE Set the Tone This Week | WEEX TradFi Daily Brief (September 28, 2026)
Global markets on September 28 enter a data and earnings window. On September 25 ET the S&P 500 rose 0.51% to 7,743.41, the Nasdaq 0.48% and the Dow 0.93%. Information technology and semiconductors outperformed; energy lagged as oil eased. The 10-year yield is about 5.15% and the 30-year about 5.5%, with October hike odds around 64%–66%. Bitcoin last traded near $84,500. Investors wait on September 30 ET PCE and Micron guidance.
PCE and Payrolls are coming |WEEX Weekly Market Hotspot (September 28-October 2, 2026)
ONDO Tokenized Smart-Portfolio Narrative Builds| WEEX TradFi Daily Brief (September 25, 2026)
Global markets on the morning of September 25 Beijing time focus on rate pricing and a split in AI infrastructure. On September 24 ET the S&P 500 was near 7,704 and almost unchanged, the Nasdaq edged higher and the Dow fell 0.31%. The 10-year yield rose to about 5.18% and the 30-year to about 5.47%. Bitcoin last traded around $84,400.
Oracle Stock vs. KRAFTON Stock: Why Are Investors Questioning Two Growing Companies?
Compare Oracle and KRAFTON stocks through their latest results, share-price questions and the different growth tests investors face in 2026.
Bitcoin Pulls Back From $87,000| WEEX TradFi Daily Brief (September 24, 2026)
Bitcoin pulled back from about $87,000 to about $84,000, with Ethereum near $2,680. S&P Global PMI on September 23 ET far exceeded forecasts. The 10-year yield broke above 5.00%, while the 5-year and 30-year touched highs last seen in 2007 and 2004. The S&P 500 and Nasdaq slipped. Energy moved with oil and crypto-treasury stocks followed bitcoin lower. Investors await earnings from COST, BB, and others.
CME Plans BCH and UNI Futures on October 19 | WEEX TradFi Daily Brief (September 23, 2026)
Global markets on September 23 focus on a Nasdaq high and an expansion of crypto futures. The Nasdaq closed higher on September 22 for a second straight closing high. Memory names such as Micron and SanDisk plus AI hardware lifted risk appetite. Brent eased to about $98 and WTI to about $94.6. Bitcoin was near $86,200 and Ethereum near $2,750. Investors are watching CME’s planned October 19 BCH/UNI futures and the impact of delayed compute-futures review on NVDA and CME.
AMD Jumps Nearly 10%, Market Cap Tops $1 Trillion| WEEX TradFi Daily Brief (September 22, 2026)
Global markets on September 22 focus on a repair in AI-compute pricing. On September 21 the three major equity indexes closed higher. AMD rose nearly 10% and its market cap crossed $1 trillion for the first time, while Intel and Arm also surged. Brent crude fell about 3.4% to $100.34 and the 10-year Treasury yield eased to about 4.96%, lowering discount-rate pressure on long-duration tech. Bitcoin briefly broke above $87,000 and total crypto market cap returned above $3 trillion. Investors next watch consumer and housing earnings plus PMI flash prints.
WEEX Exclusive:FOMC Minutes Take Center Stage as ADI Drive the Next Validation Round for AI Hardware | WEEX Weekly Market Preview (August 17-August 21, 2026)
CPI, PPI and TSMC Earnings Recap | WEEX Weekly Market Recap (2026.10.12-10.16)
WEEX Weekly Market Recap focuses on CPI, PPI, TSMC earnings, AI financing pressure, BTC’s key support, the PYTH buyback narrative, L2 and privacy-token rotation, and crypto-finance strength. Risk assets first pulled back on oil, inflation, and AI valuation pressure, then rebounded quickly after the market digested the PPI shock.
Stocks and Crypto Rebound After Hot PPI | WEEX TradFi Daily Brief (October 16, 2026)
On October 15, September PPI rose 6.3% year on year, the highest in more than four years, briefly lifting hike expectations and triggering a short drop in equities and crypto. After the market digested the print, risk assets rebounded from the sell-off and the three major indexes closed higher. Bitcoin briefly broke below $80,000 and recovered to the $82,000–$83,000 range. CoreWeave fell sharply on bond pressure and then closed higher, while crypto-finance stocks and some L2 tokens strengthened. October 16 focus turns to industrial production and import-export prices.
Hot CPI Lifts Hike Bets; Risk Assets Pull Back | WEEX TradFi Daily(October 15, 2026)
Major indexes closed lower on October 14, with the Nasdaq leading the decline. September unadjusted CPI rose to 3.7% year on year, above forecasts, and core CPI also beat expectations. Traders sharply raised this month’s hike probability to about 43.7% and fully priced two more hikes by the end of January. Chip stocks were sold again. Bitcoin broke below $83,000 and last traded near $81,700, while spot gold and silver fell. Crypto-related stocks were under pressure, but PYTH rose against the tape. October 15 brings PPI, retail sales and key
Meta Stock Earnings: What to Watch in Meta Platforms’ Q3 2026 Results
Meta reports Q3 2026 results on October 21. See the advertising, AI spending, margin, and guidance signals that could move META stock.
Indexes Fall as Bank Earnings Diverge| WEEX TradFi Daily Brief (October 14, 2026)
Major indexes closed lower on October 13 as mixed bank earnings and pressure on chip stocks weighed on sentiment, while Microsoft and Apple both rose to record closing highs. Citigroup fell more than 5% after trading revenue missed expectations. Bitcoin rallied to about $88,000 before stalling, while whale holdings shifted back toward accumulation. Ethereum L2 and privacy tokens strengthened. On October 14, markets will focus on CPI, bank earnings and ASML’s report.
Contents
Latest articles



Latest coin listings on WEEX


